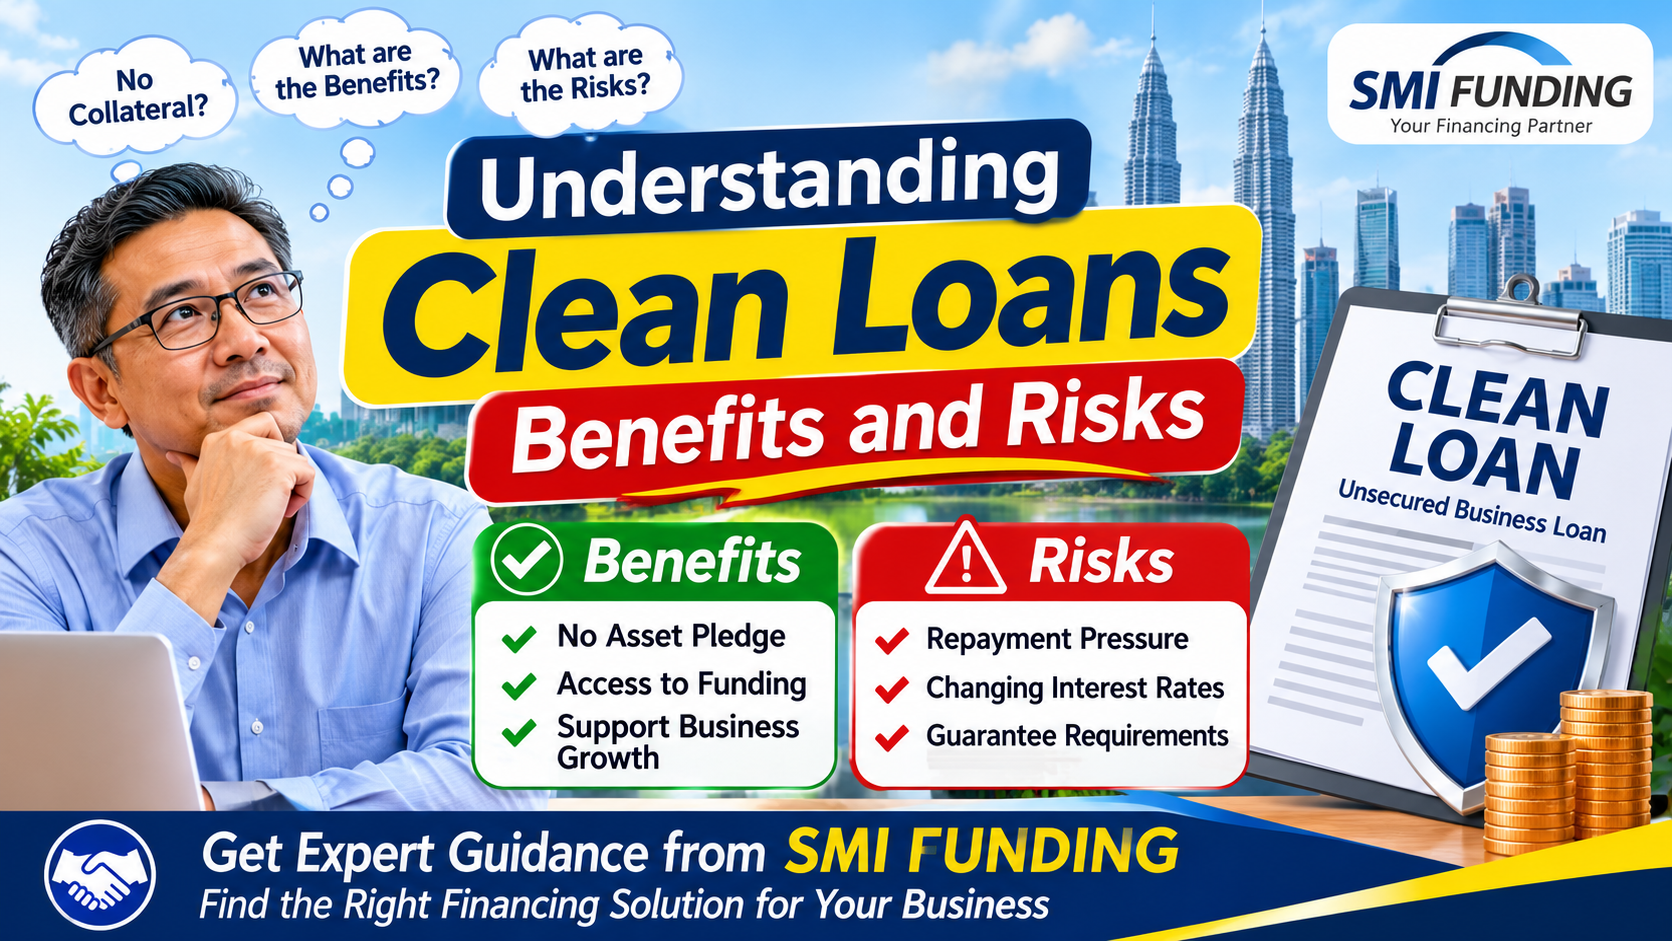
Understanding Clean Loans: Benefits and Risks
A clean loan is generally an unsecured loan that does not require an asset, such as property, to be pledged as collateral. That can make borrowing accessible to businesses without substantial assets, but it does not remove repayment obligations or possible guarantee requirements. This article explains the benefits, risks, and comparison points for Malaysian borrowers, alongside the funding consultancy support offered by SMI FUNDING
What is the clean loan meaning in practice?
The clean loan meaning is straightforward: borrowing without pledging specific assets as collateral. However, “clean” describes the security arrangement—not guaranteed approval, a clean credit record, or freedom from debt recovery. A facility can be described as clean while still requiring guarantees; Maybank’s SME Digital Financing disclosure, for example, lists director guarantees for Sdn. Bhd. borrowers and CGC guarantees where applicable.
For anyone researching clean loan Malaysia options, the practical task is to look beyond the label. Ask which assets, if any, must be pledged, who must sign a guarantee, and what obligations each signature creates. Request the product disclosure sheet and offer terms before deciding whether the arrangement fits your circumstances. An SME clean loan should also match an identifiable business purpose. Rather than starting with the largest amount available, work backwards from the expense: what needs funding, when must it be paid, and which income will repay it? Treat a business working-capital facility and personal borrowing as separate decisions, each requiring its own affordability assessment.
The benefits of borrowing without pledged assets
The main attraction is access to financing without having to offer property or another specific asset as collateral. This may be relevant when a business needs working capital but has little suitable property to pledge. Maybank’s SME Clean Loan disclosure identifies the facility as working-capital financing for SMEs and microenterprises. (hkma.gov.hk)
Consider a hypothetical wholesaler preparing for a confirmed customer order. The useful comparison is not simply whether borrowing is available, but whether the expected margin can cover financing costs and whether customer payments arrive before repayments put pressure on cash flow. The loan should support the transaction rather than consume its benefit.
Potential advantages are worth evaluating against practical needs:
- No asset pledge: Useful when you cannot—or prefer not to—offer specific property as security. Confirm guarantee requirements separately.
- A defined working-capital purpose: Match the amount requested to stock, supplier payments, or another permitted business expense.
- Digital convenience: Where an online application is available, compare its requirements with the records you already hold.
- Potentially faster access: Ask what must happen between an initial decision, acceptance of the offer, and actual receipt of funds. (maybank2u.com.my)
Speed deserves particular care. Maybank advertises accelerated approval and disbursement for qualifying digital financing applications, but its conditions distinguish between customer categories and facilities. Treat Fast Disbursement as a conditional benefit, not a promise that every applicant receives money immediately. (maybank2u.com.my)
What risks should you assess before accepting a clean loan?
The central risks are repayment pressure, changes in borrowing costs, and obligations that remain despite the absence of pledged assets. Maybank’s disclosures describe variable-rate borrowing, guarantee requirements, and consequences of missed payments. “Unsecured” should therefore never be read as “risk-free.” (maybank2u.com.my)
Repayment pressure & changing costs
Build your assessment around cash available after essential expenses, existing debt payments, and necessary reserves. Avoid using gross sales as a substitute for repayment capacity. For example, ask whether you could still make the instalment if a major customer paid late or a supplier required earlier payment.
Variable pricing needs an additional check. Maybank’s digital financing disclosure states that changes in the reference rate can affect instalments and total repayment. Request an illustration showing what a higher rate would mean for your proposed borrowing, rather than assuming the opening instalment will remain unchanged. (maybank2u.com.my)
Guarantees and default consequences
Read every guarantee before signing and seek clarification if the wording is unclear. Establish who is responsible, what the guarantee covers, and how it ends.
Maybank’s SME Clean Loan disclosure identifies director guarantees for relevant company borrowers, making this a separate issue from whether property is pledged. (maybank2u.com.my) Missed payments can also trigger contractual charges and recovery measures. Maybank’s digital financing disclosure includes late-payment provisions, default pricing, and rights of set-off. If repayments become difficult, contact the lender early to discuss available alternatives instead of waiting for arrears to build. (maybank2u.com.my) Read promotional claims as prompts for verification Advertising language can draw attention to a useful feature, but it cannot replace the agreement. Treat each claim as something to confirm in writing. In particular, do not allow urgency to displace checks on suitability, costs, or the provider’s identity. • “100% Clean Loan” and “No Collateral”: Ask whether this refers only to asset security and whether guarantees remain necessary. • “Fast Disbursement”: Confirm eligibility, outstanding conditions, and when funds become available for use. • “First Come First Serve” and “Limited Fund”: Request the scheme name, allocation rules, and evidence that the stated restriction applies. Some financing programmes genuinely depend on available funding; Maybank’s disclosure specifies this for certain programme-linked facilities. That does not establish that every clean loan has a restricted allocation or operates on a queue basis. Verify the particular offer rather than generalising from promotional wording. (maybank2u.com.my) Also verify the provider independently before sharing sensitive records or transferring money. Bank Negara Malaysia warns that loan fraudsters may use false licensing claims and request initial payments described as administrative, stamp-duty, or legal expenses. Check the relevant official records and confirm suspicious requests through independently obtained contact details. (bnm.gov.my)
SMI FUNDING’s role in the application journey
SMI FUNDING provides consultancy services related to funding resources available in the market. Its consultants help identify the best-fitting loan products for clients’ business or personal needs, prepare loan applications, submit them, and assist according to loan-provider guidelines through the process toward approval and disbursement. This support is not a guarantee of approval or preferred terms. (smifunding.com)
A crucial distinction applies to Maybank
Before engaging consultancy support, agree on the scope, fees, submission permissions, and handling of personal documents. Bring a clear funding purpose, an affordable repayment estimate, and an honest account of existing commitments. Ask what happens if a provider declines the application or offers different terms.
A crucial distinction applies to Maybank: the bank states that it does not appoint third parties to act on its behalf for SME Digital Financing applications and that no handling fees or commissions should be paid to agents or advisers for those applications. Independent consultancy should not be presented as bank authorisation. (maybank2u.com.my)
Choose suitability over speed
Before proceeding, write down the funding purpose, net amount needed, repayment source, and obligations you are prepared to accept. Compare those requirements against the written offer, not just the headline benefit. Contact SMI FUNDING to discuss suitable funding resources and its consultancy scope, while confirming lender-specific terms directly with the provider.
About
Loan Application Support for SMEs & Individuals By SMI FUNDING
+60 1158 6133 90
info@smifunding.my
Company
Working Hours
Mon - Fri: 10:00AM - 06:00PM
©2026 SMIFINANCING.COM. All Rights Reserved
Life at SMI FUNDING